Serving Louisiana, Mississippi & Texas property owners Call 844.975.2100 · Book a phone consultation
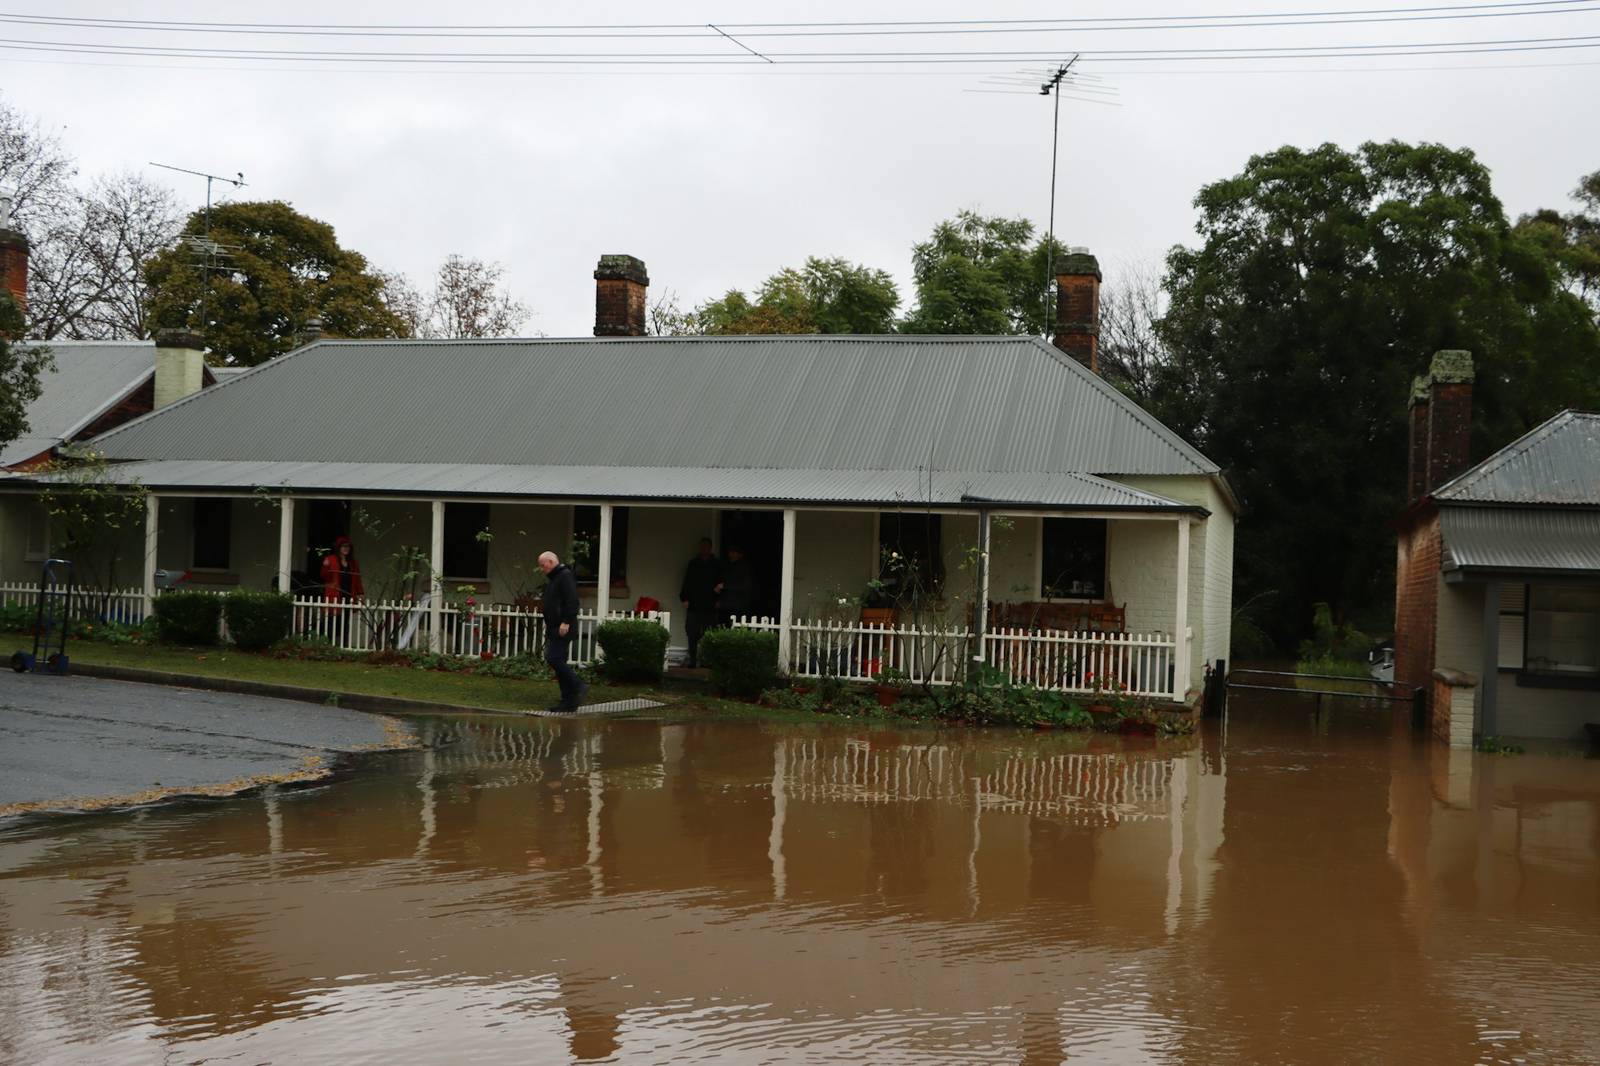
House surrounded by flood water
Flood claims

Flood insurance claims, without the guesswork

Flood claims follow their own rules. Most flood policies are written through the National Flood Insurance Program (NFIP), with strict deadlines, specific coverage limits and a lot of paperwork. We help you get it right.

Common problems

What makes flood claims different

Homeowners policies exclude flood

Rising water from outside is usually only covered by a separate flood policy, either NFIP or private flood.

Strict deadlines

NFIP policies require a signed proof of loss within a set time, usually 60 days after the loss unless FEMA extends it. Missing it can cost you the claim.

Coverage limits

NFIP residential policies cap building coverage at $250,000 and contents at $100,000, so documenting every item matters.

Wind or water?

After a hurricane, wind damage goes to your homeowners carrier and flood damage to your flood carrier. Disputes over which caused what are common.

Limited basement and below-floor coverage

Some areas of the home and some contents have limited coverage under the standard flood policy.

Increased Cost of Compliance

If local rules require you to elevate or rebuild to code, NFIP's ICC coverage may pay up to $30,000.

Flooded house
What we document

A complete claim, from the start

We inspect the property, write a line-by-line Xactimate estimate and handle the back-and-forth with your insurance company for homes, businesses and churches.

  • Water line measurements in every room
  • Building damage room by room
  • Contents inventory with photos
  • Wind versus flood damage separated
  • Proof of loss prepared on time
  • Code and elevation requirements reviewed
Questions we hear

Frequently asked questions

Does my homeowners policy cover flood?

Usually not. Water rising from outside the home is excluded from most homeowners policies and is covered by a separate flood policy, if you have one.

I have both a flood policy and a homeowners policy. Who pays?

It depends on what caused each part of the damage. Wind damage goes to the homeowners policy and flood damage to the flood policy. We document both so neither carrier can push the loss onto the other.

What is a proof of loss?

It is a signed, sworn statement of the amount you are claiming. NFIP requires it within a deadline, so it should be filed on time even while the claim is still being adjusted.

My flood claim was denied or underpaid. What now?

The NFIP has an appeal process with its own deadline. Contact us quickly with your denial letter so we can review your options.

Flood Claims

Talk to us about your claim

844.975.2100

Or email claims@oceanstates.net with photos and any letters from your insurance company.